


Global FoodTech investments in 2026
The centres of gravity are changing
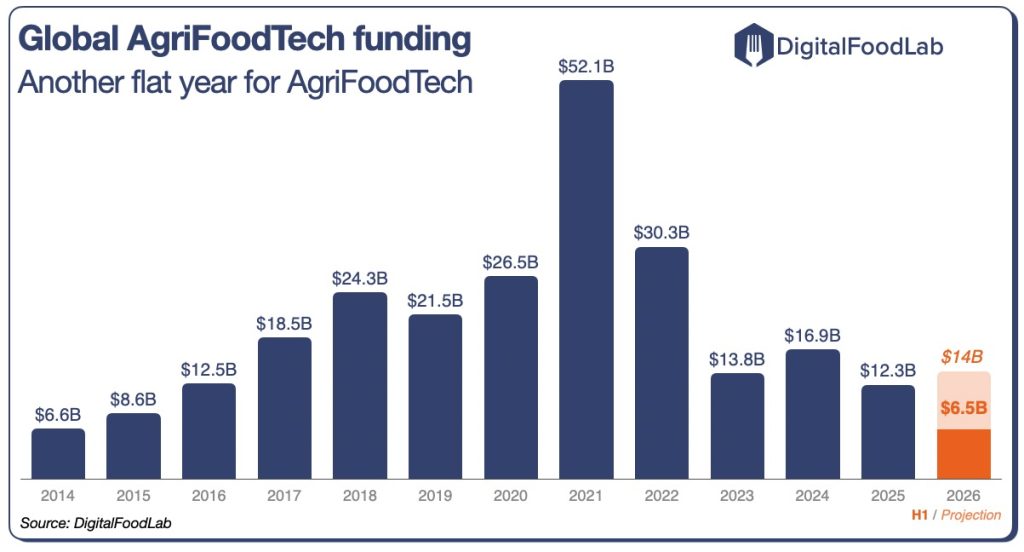
Funding fell again in 2025, while a sustained recovery remains unconfirmed. DigitalFoodLab’s data shows $12.3 billion invested in 2025, approximately 27% below 2024. The first half of 2026 brings encouraging signals, but these do not yet establish a lasting recovery.
The centre of gravity is increasingly shifting towards agriculture and food products. AgTech and Food Science together account for 64% of funding in H1 2026, compared with 13% for delivery (compared to more than 50% a few years ago).
Three developments shaping the next FoodTech cycle
Health-focused nutrition is becoming a field for growth and acquisitions. Categories linked directly with GLP-1 (dietician platforms) and indirectly (better-for-you brands, supplements) are rising at an unprecedented speed and are becoming a key target for acquisitions. Agrifood companies should identify the benefits, formats and consumer relationships that could reshape their portfolios.
Agricultural investment is targeting productivity and resilience: despite the decline in overall AgTech funding, companies such as Halter, Targan and Tropic continue to attract capital. Their solutions address production efficiency and crop performance, with answers to labour shortages and supply reliability. Their progress will depend on adoption under real farming conditions and the economic benefits they deliver to users.
Commercial launches are ushering in a new phase for novel ingredients: we observe progress towards the commercial use of ingredients developed with alternative protein technologies. Successful applications could support further industrial partnerships and investment, even as the wider alternative protein ecosystem continues to consolidate.


